Two questions come up in almost every call I take, so as in the last two reports I am answering both before showing you a single chart. This report follows my September market report, and every section tells you what changed since then.

There is one new section this month. A number about the brokerage market itself went round LinkedIn this week: 2,226 agencies gone from Dubai's public register since March. I put it next to the Land Department's own base, explain what it does and does not show, and what it means if you are about to pay a deposit. If you would rather have the two-page PDF I send to clients, it is at the end of this article.
Is it a good time to buy property in Dubai?
Activity turned up in October, and that is the headline of this report. Deals rose 5.3 percent on September, the first monthly rise since June. Sales value rose faster, 14.4 percent, to Dh34 billion, because the average deal grew to Dh2.85 million. Villa and plot deals are now above last year.
Prices barely moved. The citywide price per square foot was 1 percent lower than September, at Dh1,640, and that is still the second-highest October reading since 2014. This market has not got cheap, and it is not running away from you either.
The other half: deal counts are still about 40 percent below October 2025. That gives a buyer room to compare, and no reason to rush. Developers are offering discounts, DLD fee waivers and flexible payment plans, and those offers are easiest to judge side by side, which is what our monthly Expo is for. None of this is a forecast. The right decision still depends on your budget, your timeline and the specific unit.
Should I sell my property, or hold and rent it out?
It depends on the asset, and this month the gap between assets is wide.
Resale apartments edged up for a fourth month, to a median Dh1,522 per square foot. Resale townhouses are 1.8 percent above last year and resale plots 35 percent above. If you own one of those, you are not selling into weakness.
Rents are softer. The median apartment rent eased to Dh67,800 a year, 5.8 percent below last year, and townhouse rents are 2.9 percent below. Commercial rents are the exception, at 23.3 percent above last year. If you hold for income, your building and your unit type matter far more than the citywide average. Message me about your property and I will look at your building's own numbers.
October against what I wrote in September
Last month's report reached specific conclusions. Here is each one next to October's data.
| In September I wrote | October shows |
|---|---|
| The deal count fell for a second month | Reversed: deals rose 5.3%, the first rise since June |
| The average deal grew to Dh2.60M | Grew again, by 9.4%, to Dh2.85M |
| Villas, plots and commercial grew | Villas and plots grew far faster; commercial was flat |
| Resale apartments rose a third month and were 1.6% above 2025 | Rose a fourth month, to Dh1,522, but are now 2.1% below October 2025 |
| Off-plan apartments were 4.8% below 2025, 12.5% over resale | Only 1.7% below 2025, and 12.9% over resale |
| Apartment rent was Dh70K, 4.1% below last year | Dh67.8K, 5.8% below |
| Mortgages came back, value up 12.7% on August | Mortgage count up 8.0%, value down 22.1% |
| 33% of deals were above Dh2M | 36% |
| 64% of deals were a purchase from a developer | 64% again, but 56% of value, up from 53% |
| Year-on-year numbers would stay deeply negative through December | As expected: deals 39.9% and value 42.6% below last October |
| Dubai South was first, Al Barsha South Fourth close behind | They swapped: Al Barsha South Fourth, which is JVC, is now first |
Two conclusions reversed: the falling deal count and the recovery in mortgages. Two got stronger: bigger tickets and the villa market. One trend sped up, and it is the one to watch: apartment rents.
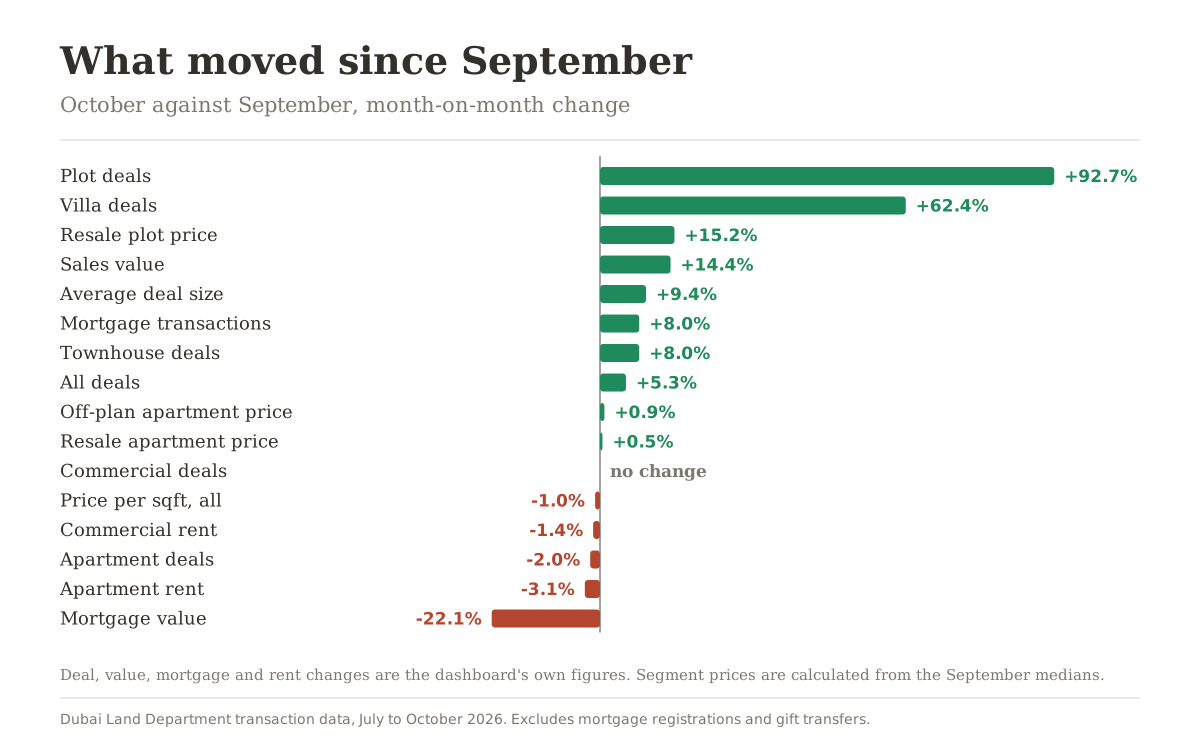
Dubai property market, October 2026, in four numbers
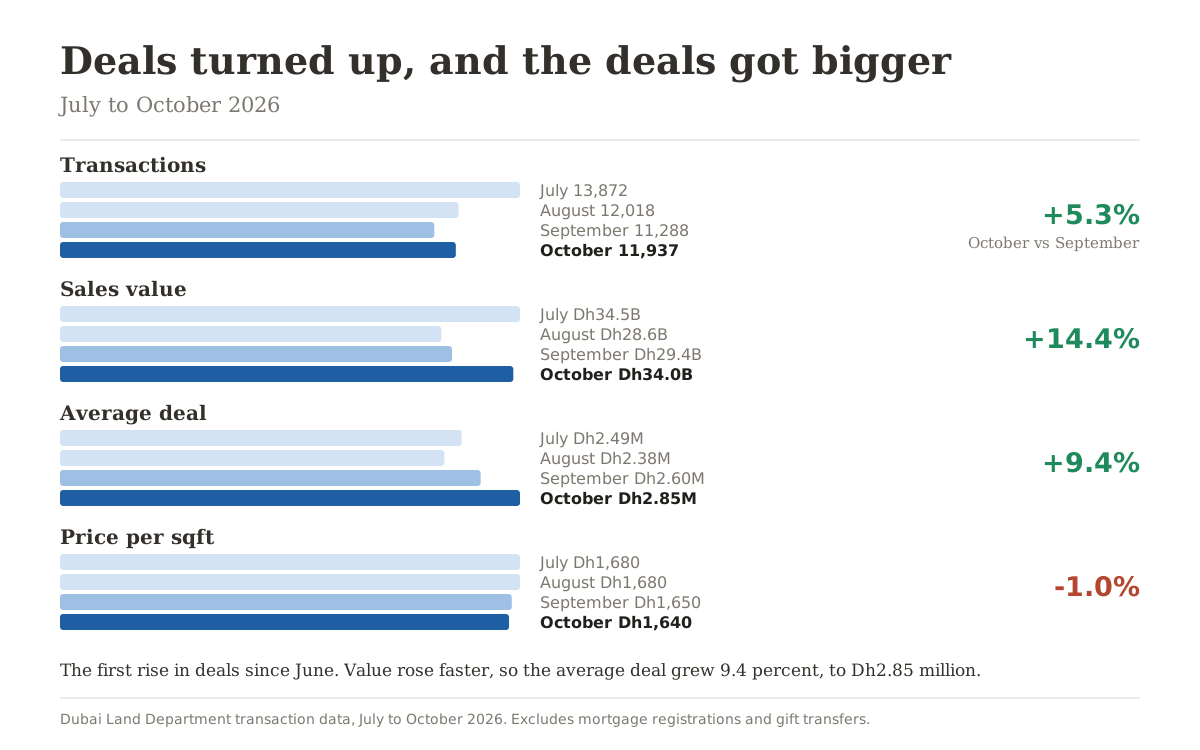
| Metric | July | August | September | October | vs September | vs Oct 2025 |
|---|---|---|---|---|---|---|
| Transactions | 13,872 | 12,018 | 11,288 | 11,937 | +5.3% | -39.9% |
| Sales value | Dh34.5B | Dh28.6B | Dh29.4B | Dh34B | +14.4% | -42.6% |
| Price per sqft | Dh1,680 | Dh1,680 | Dh1,650 | Dh1,640 | -1.0% | -3.7% |
| Average deal | Dh2.49M | Dh2.38M | Dh2.60M | Dh2.85M | +9.4% | not calculated |
The four lines moved more in step this month than in the last two. Deals had fallen from 13,872 in July to 11,288 in September and came back to 11,937. Value rose almost three times as fast as the deal count, from Dh29.4 billion to Dh34 billion. That is close to July's Dh34.5 billion, on about 1,900 fewer deals.
When value rises faster than volume, the deals got bigger. The average went from Dh2.38 million in August to Dh2.60 million in September and Dh2.85 million in October. It did not come from a higher price per square foot, which slipped 1 percent. It came from the mix moving towards villas and plots, which the next section puts a number on.
The year-on-year comparison is still heavy, and I am not going to soften it. Deals are 39.9 percent and value 42.6 percent below October 2025. Last October had about 19,900 deals, one of the busiest months this market has recorded, so much of that gap is last year's high bar rather than this year's weakness.
Where the extra Dh4.6 billion came from
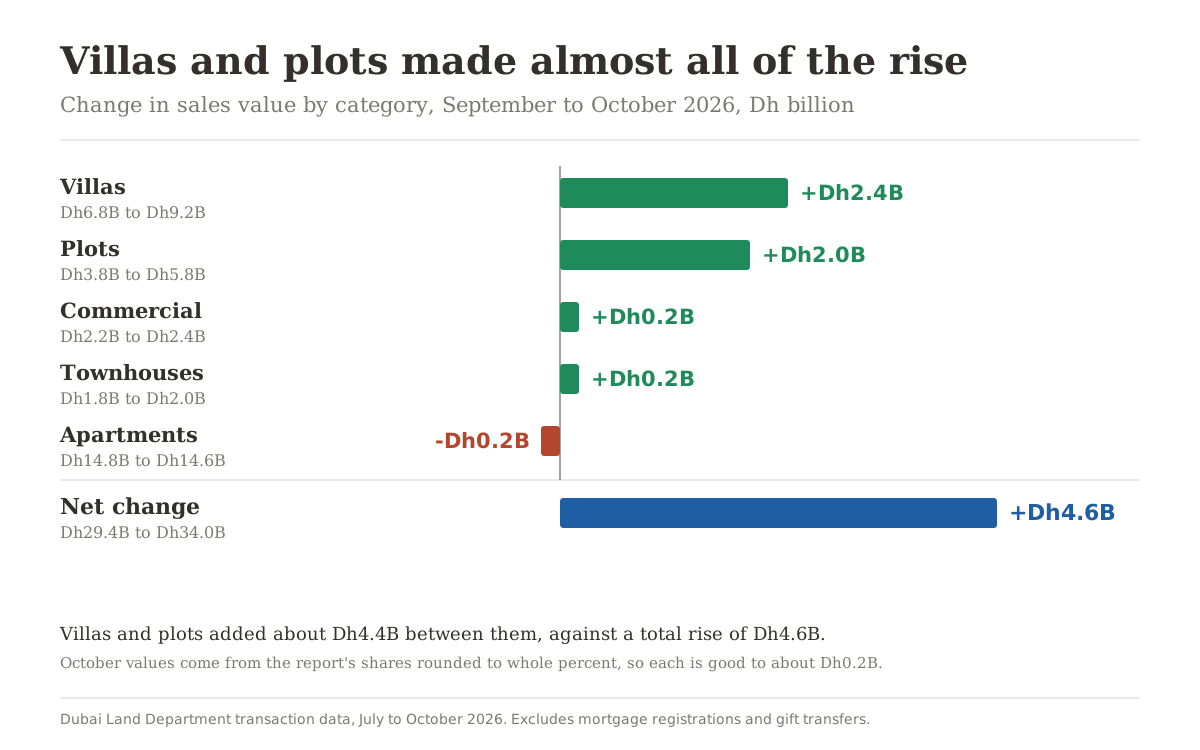
The October report gives each category's share of total value. Apply those shares to Dh34 billion and set them next to September, and the picture is clear.
- Villas went from about Dh6.8 billion to about Dh9.2 billion.
- Plots went from Dh3.8 billion to about Dh5.8 billion.
- Commercial and townhouses each added about Dh0.2 billion.
- Apartments lost about Dh0.2 billion.
Villas and plots added about Dh4.4 billion between them, against a total rise of Dh4.6 billion. The apartment share of value fell from 50 percent to 43 percent, villas rose from 23 to 27 percent and plots from 13 to 17 percent.
The October figures come from shares rounded to whole percent, so each is good to about Dh0.2 billion. The conclusion survives that margin: October's extra value came almost entirely from villas and plots.
Villa and plot deals are now above last year
| Category | Deals in October | vs September | vs Oct 2025 |
|---|---|---|---|
| Plots | 449 | +92.7% | +16.0% |
| Villas | 1,356 | +62.4% | +5.5% |
| Townhouses | 649 | +8.0% | -48.9% |
| Commercial | 540 | no change | -21.5% |
| Apartments | 8,888 | -2.0% | -45.2% |
From October the dashboard reports townhouses separately from villas. Until now the villa count included them, and September had 1,428 villa deals on that definition. October's villas and townhouses together come to 2,005, about 40 percent more than September even on the old definition.
The last column matters more. Villa deals are 5.5 percent above last October and plot deals 16 percent above, in a market that is about 40 percent below. The annual fall sits almost entirely in apartments and townhouses, and apartments, at 8,888 deals, are still about three quarters of everything the city traded. A large part of the villa jump came from one project, which I come to in the best-sellers section.
Dubai property prices in October 2026: off-plan vs resale
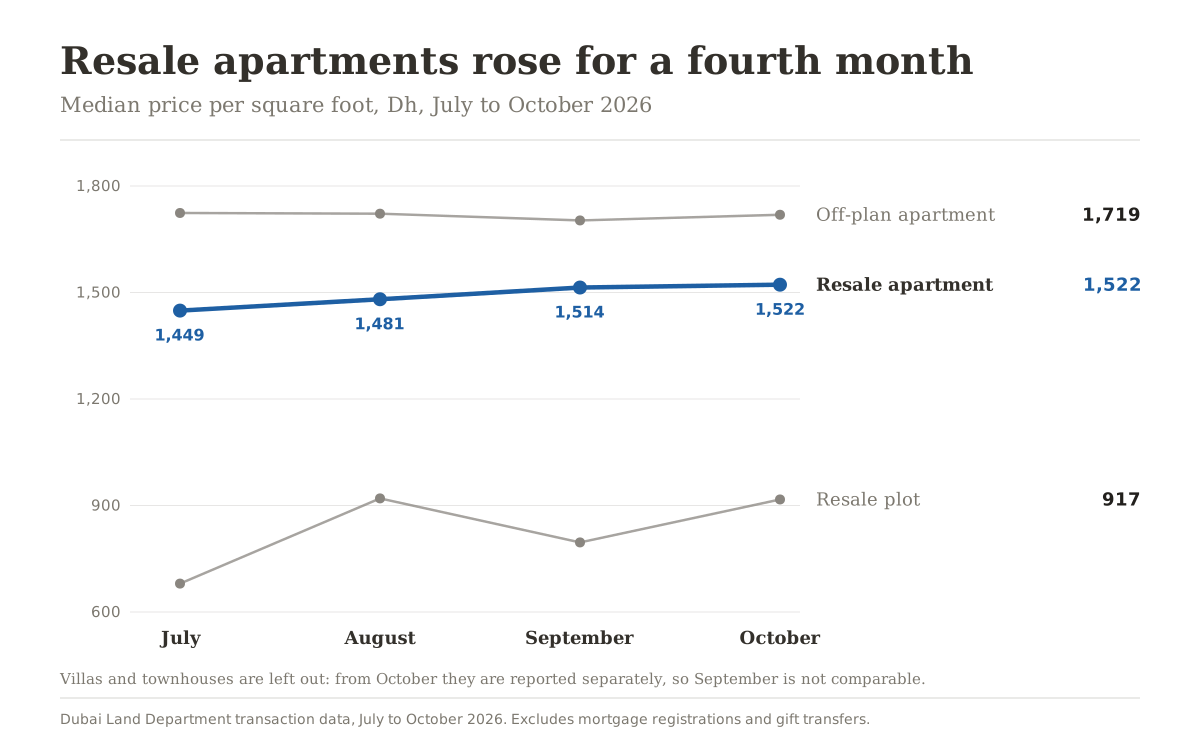
| Type, Dh per sqft | Off-plan | vs Sep | vs 2025 | Resale | vs Sep | vs 2025 |
|---|---|---|---|---|---|---|
| Apartment | 1,719 | +0.9% | -1.7% | 1,522 | +0.5% | -2.1% |
| Villa | 1,236 | not comparable | -30.2% | 1,631 | not comparable | -2.4% |
| Townhouse | 1,615 | newly reported | -7.4% | 1,532 | newly reported | +1.8% |
| Plot | left out | left out | left out | 917 | +15.2% | +35.3% |
Apartments are the only type up on September in both off-plan and resale. The resale median has gone Dh1,449, Dh1,481, Dh1,514 and now Dh1,522. The pace slowed to half a percent, but the direction has not changed in four months.
One reading needs care. Resale apartments were 1.6 percent above last year in September and are 2.1 percent below it now, even though the price itself rose this month. October 2025 was simply a higher base to compare against. The market did not go backwards in October.
Villas and townhouses cannot be compared with September this month. Splitting townhouses out changed the villa median, and the 30.2 percent fall in off-plan villas against last year mostly reflects which projects sold this month, not a real price fall. Off-plan plot medians read Dh540, Dh48, Dh300 and Dh468 over four months, so I have left them out.
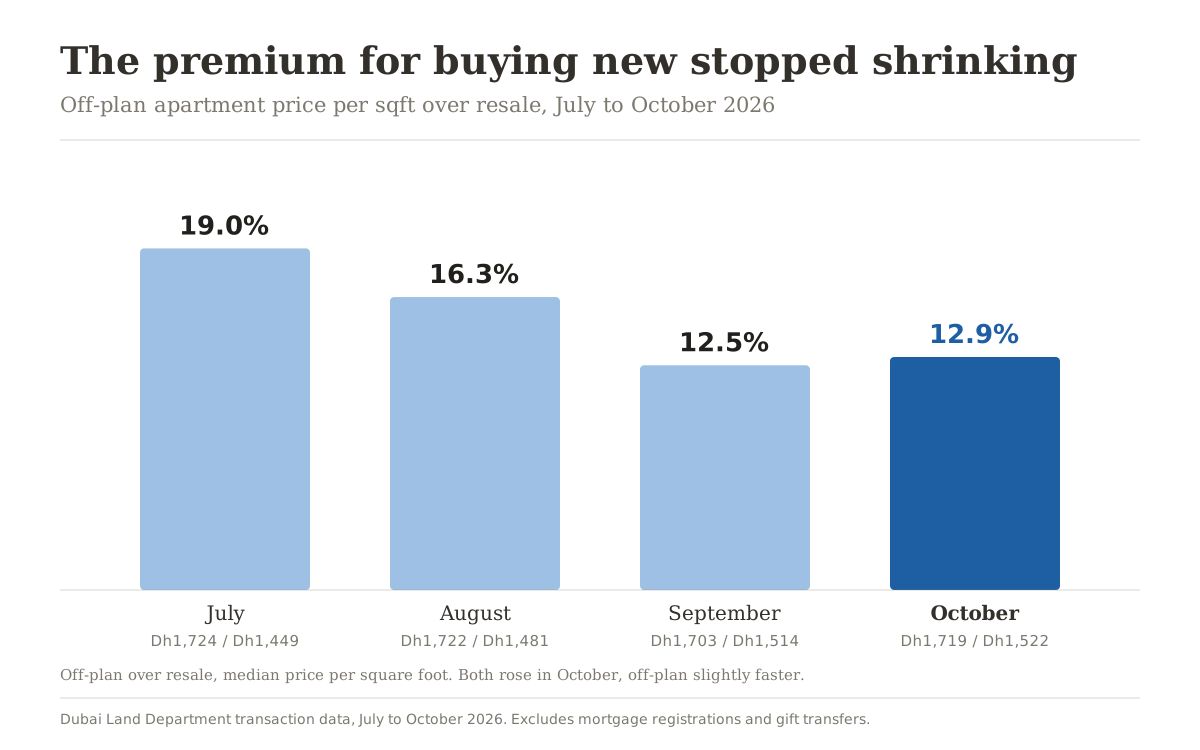
The premium for buying a new apartment rather than a resale one had shrunk three months running: 19.0 percent in July, 16.3 in August, 12.5 in September. In October it stopped, at 12.9 percent, because off-plan prices rose slightly faster than resale. The two medians come from different buildings and districts, so do not read the exact figure too closely. The practical point holds: the extra you pay for new is no longer falling, so put a completed unit in the same area next to any off-plan price. I set out the full comparison in off-plan vs ready property in Dubai.
The second-highest October since 2014
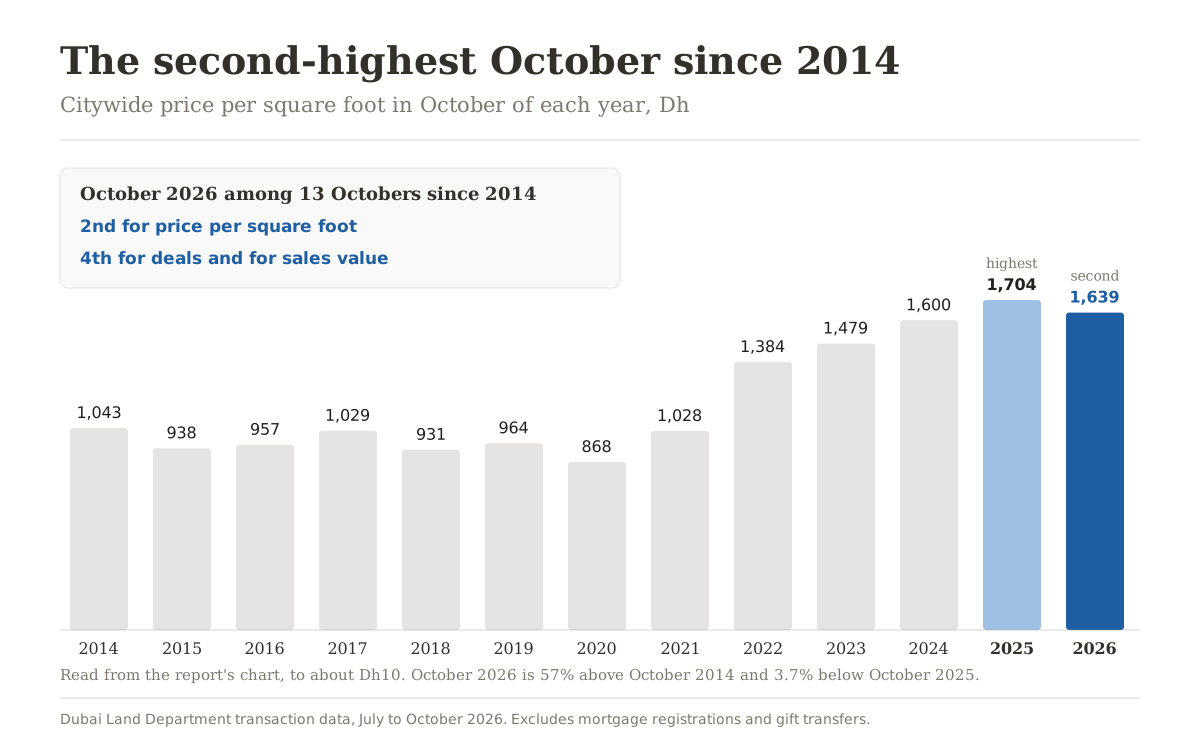
Put the Octobers side by side and the price per square foot has gone from about Dh1,043 in October 2014 to Dh1,639 in October 2026, about 57 percent in twelve years. The only higher October was 2025, at about Dh1,704. Among the thirteen Octobers since 2014, this one ranks second for price per square foot and fourth for both deals and sales value.
The chart shows two different markets. From 2014 to 2021 the October price moved between about Dh870 and Dh1,040 and went nowhere in seven years. From 2022 it rose every year until 2025. October 2026 is the first October below the year before since 2020, but by 3.7 percent, not a return to the old range.
Thirteen months of deals, and the next two comparisons
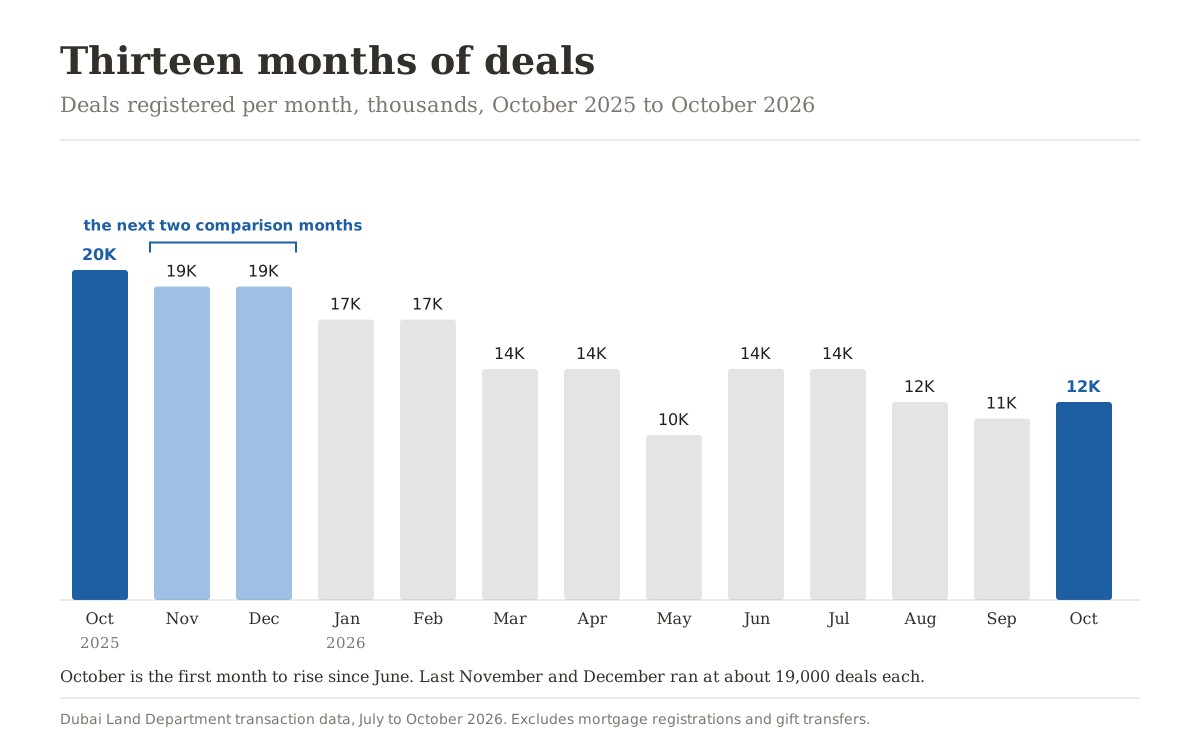
Monthly volume came down from about 20,000 deals in October 2025 to 10,000 in May 2026, recovered to about 14,000 in June and July, then fell for three months. October is the first month to turn that around.
In September I wrote that the year-on-year numbers would stay heavy to the end of the year, and October did exactly that. The same applies to the next two reports, because last November and December had about 19,000 deals each. Even if the market improves month to month, the annual change will most likely stay deeply negative through December. That is not a forecast of the market. It is arithmetic about the comparison months.
More than a third of deals are now above Dh2 million
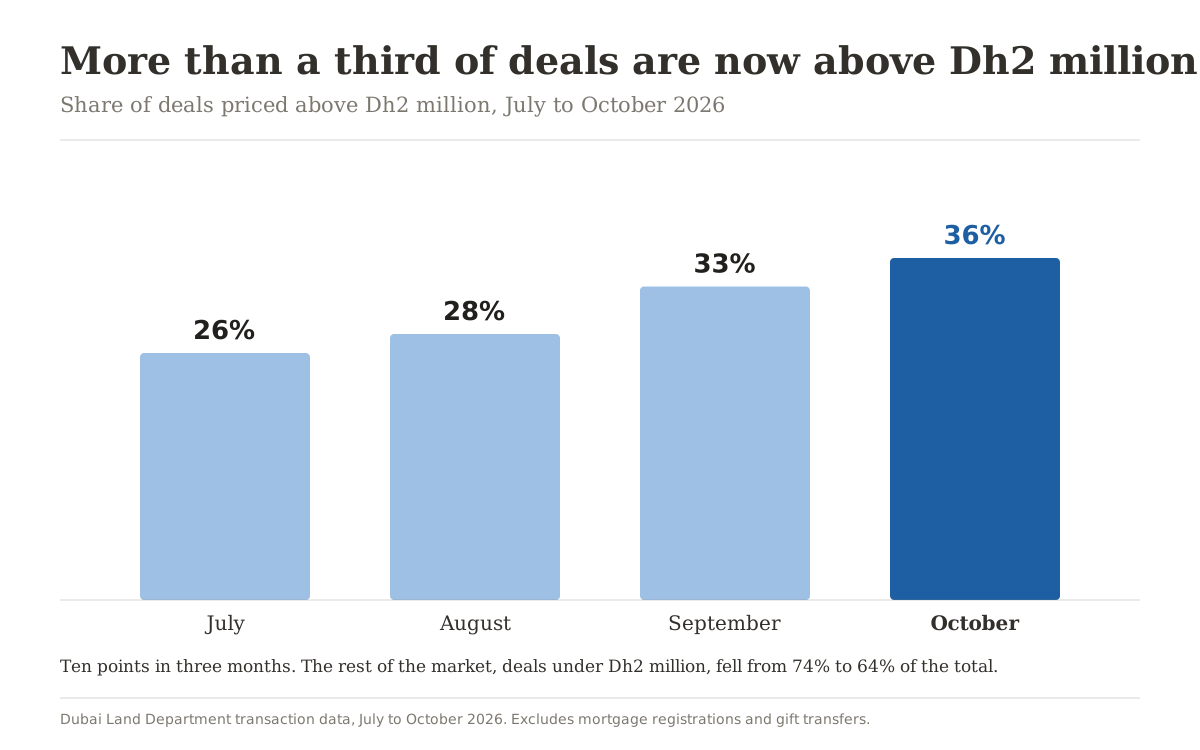
Deals above Dh2 million were 26 percent of the total in July, 28 percent in August, 33 percent in September and 36 percent in October. Ten points in three months is the market moving upmarket, and it is why the average deal rose while the price per square foot held still. By deal count Dubai is still a sub Dh2 million market, with 64 percent of deals below that line, but that share falls every month.
The same shift shows up in the off-plan share. Purchases from a developer were 64 percent of deals in October, the same as September, but 56 percent of value, up from 53. Apply those shares to the totals and the average off-plan deal rose from about Dh2.2 million in September to about Dh2.5 million, while the average resale deal stayed around Dh3.4 to Dh3.5 million. The bigger tickets came from the off-plan side, which means new villa launches. The shares are rounded, so treat those averages as approximate.
Dubai rents in October 2026, and the sell-or-hold arithmetic
| Type | Median annual rent | vs September | vs Oct 2025 |
|---|---|---|---|
| Apartment | Dh67,800 | -3.1% | -5.8% |
| Villa | Dh214,500 | not comparable | -4.7% |
| Townhouse | Dh165,000 | newly reported | -2.9% |
| Commercial | Dh113,900 | -1.4% | +23.3% |
For anyone holding property for income, apartment rent is the number in this report. The median was about Dh70,000 in September and Dh67,800 in October, and the gap to last year widened from 4.1 to 5.8 percent.
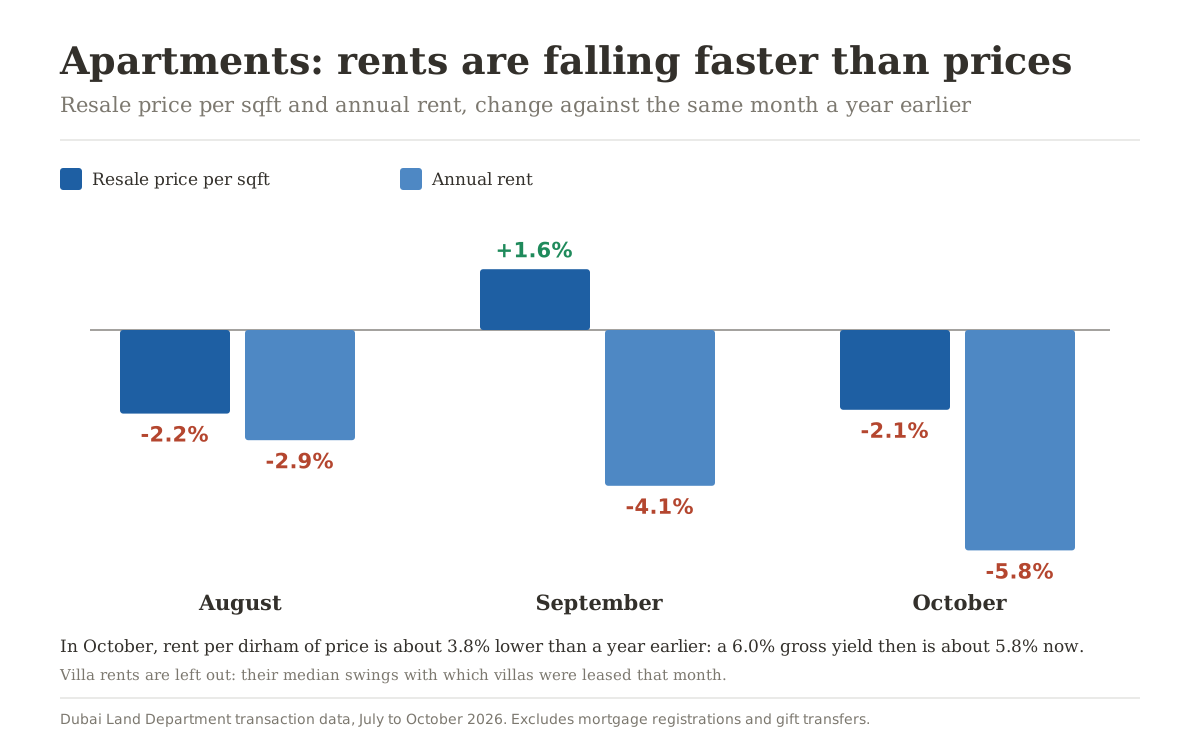
When rent falls faster than price, the yield thins. In October, resale apartment prices are 2.1 percent below last year and rents 5.8 percent below. Put together, the rent you get for each dirham of price is about 3.8 percent lower than a year ago. In plain terms, an apartment that yielded 6.0 percent gross last year yields about 5.8 percent on today's numbers. That is not dramatic. But if you bought with a mortgage, a few tenths of a percent can decide whether the rent covers the instalment.
Villa rents move with which villas were leased each month, and the townhouse split has changed the definition too, so I read them by direction only: below last year. Commercial rent is the one segment above last year, and at 23.3 percent it is a different story from the residential market. To work out a specific unit's yield, put that building's actual rent into the rental yield calculator, not the citywide median.
Dubai mortgages in October: more loans, smaller ones
| Metric | September | October | vs September |
|---|---|---|---|
| Mortgage transactions | 4,038 | 4,604 | +8.0% |
| Mortgage value | Dh16.2B | Dh13.2B | -22.1% |
More mortgages were registered in October, for less money in total. Divide value by count and the average registered mortgage fell from about Dh4.0 million in September to about Dh2.9 million. A swing that size in one month usually means September carried a few very large registrations, not that buyers suddenly borrowed less. The resale buyer mix did not move: 68 percent paid cash and 32 percent used a mortgage, the same as September.
If you are buying with finance, get your approval in principle before you reserve a unit. The mortgage calculator shows the loan to value cap for your buyer type and the cash you need on the day, fees included.
Best-selling projects in Dubai, October 2026
The October report ranks the off-plan projects that registered the most units, apartments and villas separately. The last column is the same project's count in September, where it was on that month's list.
| Off-plan apartments | Units in October | Median price | Units in September |
|---|---|---|---|
| Binghatti Skyterraces | 208 | Dh1.1M | 252 |
| Raw District 2 by Imtiaz | 176 | Dh747,200 | 186 |
| Garden Living | 160 | Dh900,500 | not listed |
| Off-plan villas | Units in October | Median price | Units in September |
|---|---|---|---|
| Tilal Binghatti | 336 | Dh1.5M | not listed |
| Greenz by Danube | 93 | Dh4.5M | 62 |
| The Greens at Sobha Sanctuary | 43 | Dh4.2M | 51 |
The story in these tables is Binghatti. Its three projects on October's lists, Tilal Binghatti, Skyterraces and Skyflame 1, registered 661 units worth about Dh991 million. That is about 5.5 percent of every deal in the city this month, from three projects by one developer. Tilal Binghatti alone sold 336 villas, about a quarter of all October villa deals, which explains a large part of the 62 percent jump in villa deals. Skyflame 1 made up 117 of the 661, down from 226 in September.
Greenz by Danube rose from 62 units to 93, at the same Dh4.5 million median both months. RAW District 2 by Imtiaz held its place with 176 units at a median of about Dh747,000, still the cheapest project on these lists. Binghatti Skyterraces' median moved from about Dh840,000 to Dh1.1 million, which says more about larger units selling this month than about a price rise.
On the resale side, Dune Residency Dubai (38 units) and Regalia (30) led apartments, and Lunaya led villas with 21 units at a median of Dh6.7 million.
The top end: a Dh97 million villa
The most expensive sale of the month was a Dh97 million villa in Eden Hills. The most expensive apartment was Dh55 million at Balqis Residence on Palm Jumeirah. Two sales barely move a citywide average, but they show that the top of the market is active in a month when total deal counts are still low.
Where the deals happened
The five most active areas by deal count in October, in rank order:
- Al Barsha South Fourth, which is JVC
- Dubai South
- Al Rowaiyah First
- Wadi Al Safa 3
- Wadi Al Safa 5
These are the Land Department's official land-registry districts, which do not always match a community's marketing name. Dubai South led in July, August and September, and in September it was only just ahead of Al Barsha South Fourth. In October they swapped, and JVC took first place. Al Rowaiyah First is new to the top five, and Jabal Ali First, fourth in September, dropped out. The JVC rental yield and price page has that community's own numbers, and I looked at Dubai South on its own in is Dubai South a good investment?
2,226 Dubai real estate agencies left the register: what it means for you
On 11 November a LinkedIn post by Fateh Al-Msaddi drew a lot of attention. Using the Land Department's public data on DXB Interact, it reported that 2,226 real estate agencies that were on the record in March 2026 no longer appeared on 10 November. The author was clear that he does not know why, and that the count includes only agencies that no longer hold a licence.
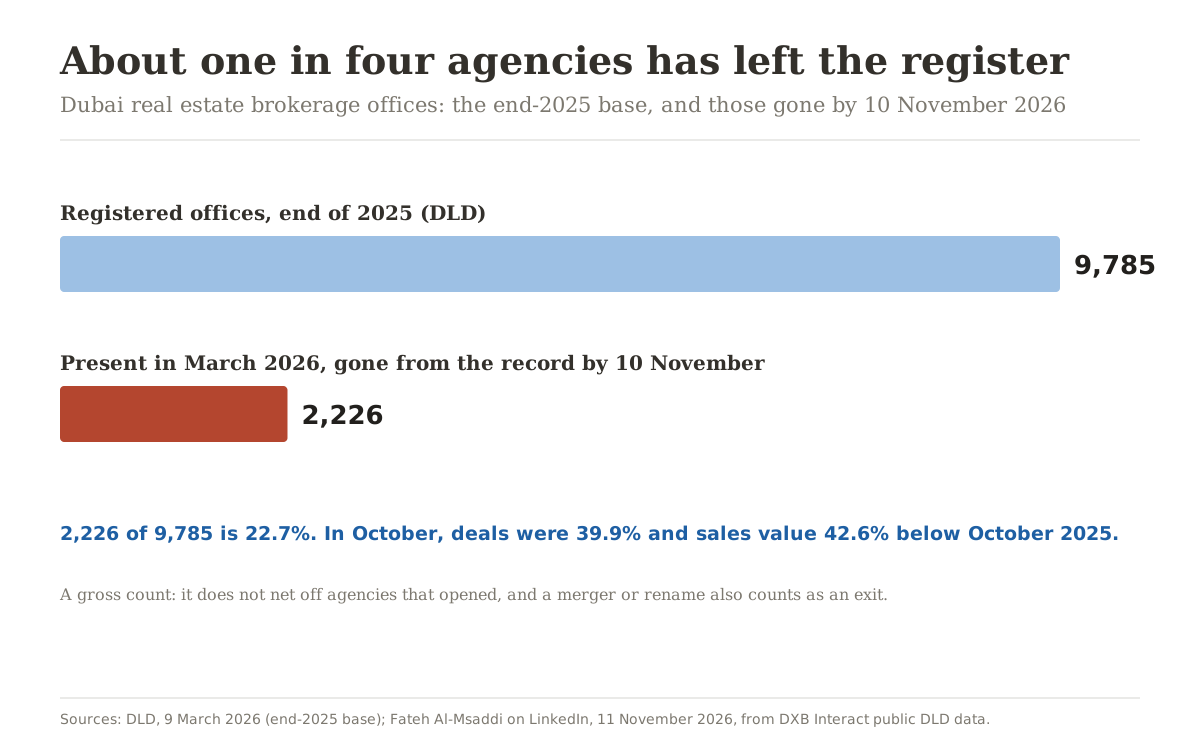
The post does not say what the number fell from. The Land Department does: on 9 March 2026 it reported 9,785 registered brokerage offices and 32,294 registered brokers at the end of 2025. On that base, 2,226 is about 23 percent. Roughly one office in four.
Three cautions before reading anything into it.
- It is a gross figure. Agencies that opened in the same period are not netted off, so the net fall is smaller.
- A merger, a rename or a licence moved to a new company also counts as an exit. Not every exit is a closure.
- The Land Department's base and the DXB Interact record are not the same list, so treat the 23 percent as an estimate.
The direction fits the market data all the same. 2025 was the busiest year this market has seen. The Land Department's same release counted 13,083 new brokers that year, up 38 percent, Dh13.59 billion in brokerage commissions and 96,440 broker-executed transactions. That is about ten transactions per office in the best year on record. This October, deals were 39.9 percent and value 42.6 percent below last October. An office's income moves with deals; its rent, licence renewal and listing costs do not. A market that grew quickly in a boom year is getting smaller and more concentrated in a slower one.
What it means for you, whether you are buying, selling or letting:
- Before you pay anything or sign anything, check that the broker and the office are licensed, using the Land Department's licensed broker search on its website or in the Dubai REST app.
- On an off-plan purchase, pay every instalment straight into the project's escrow account, never into a brokerage's account.
- On a resale purchase, agree in writing who holds the deposit cheque until transfer.
- If you hand a property to an agency to let or sell, sign the agreement against that office's licence number.
I included this because the number is travelling without its base or its caveats. A smaller brokerage market is not good news or bad news in itself. It is a reminder that a licence check takes a few minutes, and it is worth doing before every payment.
Sky View's Expo is now monthly: the 31 October edition
Holding an Expo every month is becoming a Sky View tradition. The third Grand Property Expo ran on Saturday 31 October at the Shangri-La Dubai on Sheikh Zayed Road, with 42 developers. It came a month after September's edition sold Dh85 million in a single day. The details of the day are on the Diwali Edition page.
One cross-check is worth making. The developers behind most of this month's best-selling projects were at one of our last two Expos: Binghatti in September, and Danube, Imtiaz and Sobha in October. I am not claiming the Expo caused those numbers. It does show that the developers you meet side by side at the Expo are the ones the market is buying from. Message me on WhatsApp for the date of the next one and the offers worth comparing. If you tell me your budget and what you are looking for beforehand, I will have a shortlist of the developers that fit.
What I would do this month
Six things, based on the data above rather than on what would be convenient for me.
- If you are buying off-plan, negotiate the terms, not only the price: the payment plan, the DLD fee treatment and the unit. The premium over resale has stopped shrinking, so price a completed unit in the same area next to it. If a developer offers a discount or a DLD fee waiver, take the discount.
- If you are selling a resale apartment, prices have risen four months running. That is the market you would be selling into.
- If you are buying an apartment to rent out, work out the yield on today's rent, not last year's. Rents are 5.8 percent lower.
- If you own a villa or a plot, these are the only two types trading above last year, and resale plots are 35 percent above. Check your own community's numbers before deciding anything.
- If you need finance, get approval in principle before you reserve.
- Whoever you work with, check their licence before you pay anything, and pay off-plan money only into the project's escrow account.
Where I land
October turned the corner on activity. Deals rose for the first time since June, sales value climbed 14.4 percent to Dh34 billion, and the average deal grew to Dh2.85 million. Villa and plot deals are above last year, and the price per square foot, down 1 percent, is still the second-highest October since 2014.
The weak spot is rent. Apartment rents are falling faster than apartment prices, which makes a purchase made today yield a little less. Apartments, about three quarters of the market, are still below last year, and the annual comparisons will stay heavy until December.
Developers are still competing for buyers with discounts, DLD fee waivers and flexible payment plans, and with the cooler season under way, this is the stretch that has traditionally lifted demand. It is a market to be selective in. Not one to chase, and not one to avoid.
If you want to go through your own situation, whether that is a purchase, a sale or a building you already own, message me on WhatsApp or call me on the same number. I would rather look at your actual numbers than have you act on a citywide average.
Download the two-page October report
The two-page summary is the one I send to clients each month: the market pulse, prices by segment, rents, financing and the best-selling projects.
Dubai market report, October 2026 (PDF)
The two-page report I send to clients each month, as a PDF. Fill in your details and the download button appears here.
A note on the data
Figures are from Dubai Land Department transaction data for July to October 2026: DLD direct sales and DIFC sale transactions, excluding mortgage registrations and gift transfers. A few notes on quality, because I would rather show you the seams than a clean number I do not believe.
Month-on-month changes for deals, value, mortgages and rents are the dashboard's own figures. The dashboard calculates them against an updated September count, most likely because late registrations are added to a month after it is first published. Comparing the two published deal counts, 11,288 and 11,937, gives about 5.7 percent rather than 5.3. September's published mortgage figures were 4,038 loans worth Dh16.2 billion. Changes in segment prices against September are my own calculation from the September medians.
From October the dashboard reports townhouses separately from villas, so villa prices and rents are not comparable with September. I took September's villa value from the 23 percent share the October report gives for September, and September's townhouse value as the rest of that month's Dh8.6 billion villa and townhouse total. October's category values come from shares rounded to whole percent and are good to about Dh0.2 billion.
Off-plan plot prices read Dh540, Dh48, Dh300 and Dh468 per square foot across the four months, so I have left them out. Resale plot medians also swing on very few deals.
The October-of-each-year prices in the long-run chart are read from the report's chart and are good to about Dh10. The headline card shows October as Dh1,640 and the long-run chart as Dh1,639, a rounding difference. The off-plan and resale average deal and the average mortgage are my own calculations from shares and totals, and are approximate. The agency figures are from the Land Department's release of 9 March 2026 and the LinkedIn post of 11 November 2026, which uses DXB Interact's public data.
Figures sourced from Dubai Land Department transaction data. Provided for information only; not financial or investment advice.
Frequently asked questions
11,937 sales worth Dh34 billion. Deals rose 5.3 percent on September, the first monthly rise since June, and sales value rose 14.4 percent. Both are still well below October 2025: deals by 39.9 percent and value by 42.6 percent.
Barely. The citywide price per square foot was Dh1,640, 1.0 percent below September and 3.7 percent below October 2025. It is still the second-highest October reading since 2014. Resale apartments rose for a fourth month, to a median Dh1,522 per square foot.
Because the mix moved to villas and plots. On the report’s shares, villas and plots added about Dh4.4 billion of the Dh4.6 billion rise in sales value. The average deal grew 9.4 percent to Dh2.85 million, and 36 percent of deals were above Dh2 million, up from 33 percent.
Plots, up 92.7 percent to 449 deals, villas, up 62.4 percent to 1,356, and townhouses, up 8.0 percent to 649. Commercial was flat at 540 and apartments fell 2.0 percent to 8,888. Villa and plot deals are also above October 2025, by 5.5 and 16 percent.
For apartments, both rose in October: off-plan to a median Dh1,719 per square foot, up 0.9 percent, and resale to Dh1,522, up 0.5 percent. The premium for off-plan over resale held at 12.9 percent after shrinking for three months. Villa medians are not comparable with September because townhouses are now reported separately.
The median apartment rent is Dh67,800 a year, 3.1 percent below September and 5.8 percent below last year. Villas are Dh214,500, townhouses Dh165,000 and commercial Dh113,900. Commercial is the only type above last year, by 23.3 percent.
It depends on your building. Resale apartment prices have risen four months running, which helps a seller. Rents are 5.8 percent below last year while prices are 2.1 percent below, so the rent per dirham of price is about 3.8 percent lower: a 6.0 percent gross yield a year ago is about 5.8 percent now. If you hold for income, check your own building’s rent, not the citywide median.
4,604 mortgages were registered, 8.0 percent more than September, but their value fell 22.1 percent to Dh13.2 billion. The average registered mortgage fell from about Dh4.0 million to about Dh2.9 million, most likely because September carried a few very large registrations. Resale buyers paid 68 percent cash and 32 percent with a mortgage, unchanged.
Off-plan apartments: Binghatti Skyterraces (208 units, median Dh1.1M), Raw District 2 by Imtiaz (176, Dh747,200) and Garden Living (160, Dh900,500). Off-plan villas: Tilal Binghatti (336, Dh1.5M), Greenz by Danube (93, Dh4.5M) and The Greens at Sobha Sanctuary (43, Dh4.2M). Binghatti’s three listed projects registered 661 units worth about Dh991 million.
A Dh97 million villa in Eden Hills, and a Dh55 million apartment at Balqis Residence on Palm Jumeirah.
Al Barsha South Fourth, the Land Department district that covers JVC, ahead of Dubai South, Al Rowaiyah First, Wadi Al Safa 3 and Wadi Al Safa 5. Dubai South had led in July, August and September.
A LinkedIn post on 11 November 2026, using DXB Interact’s public Land Department data, counted 2,226 agencies that were on the record in March and no longer appeared on 10 November. Against the 9,785 brokerage offices the Land Department reported at the end of 2025, that is about 23 percent. It is a gross figure: new agencies are not netted off, and mergers and renames count as exits.
For a selective buyer, the case is reasonable. Deals turned up in October while prices held near the top of their range, and deal counts are still about 40 percent below last year, so there is room to compare. Developers are offering discounts, DLD fee waivers and flexible payment plans. None of this is a forecast; the right decision depends on your budget, timeline and the specific unit.
The Expo is now monthly. The third Grand Property Expo ran on Saturday 31 October 2026 at the Shangri-La Dubai on Sheikh Zayed Road with 42 developers, a month after September’s edition sold Dh85 million in a day. Message Houman Jalouti on WhatsApp at +971 58 686 6733 for the date of the next one.