Two questions come up in almost every call I take. As last month, I am going to answer both before showing you a single chart. This report is the follow-up to my August market update, so every section tells you what changed since then.

If you would rather have the two-page PDF I send to clients, it is at the end of this article.
Is it a good time to buy property in Dubai?
For a selective buyer, the case got stronger in September. Not everything improved, so here are both halves.
The good half first. Sales value rose to Dh29.4 billion, from Dh28.6 billion in August, even though fewer deals closed. The deals got bigger: the average ticket rose to about Dh2.6 million. Villa, plot and commercial deals all grew. Mortgage value rose about 13 percent on the month. And prices held near the top of their range: the price per square foot is the second-highest September reading since 2014.
The other half. The deal count fell again, to 11,288. The citywide price per square foot slipped 2 percent on August. This is not a market running away from a patient buyer, and there is no reason to rush.
Developers are competing for buyers with discounts, DLD fee waivers and flexible payment plans. Those offers are easiest to judge side by side, which is what our next Expo, on Saturday 31 October, is for. None of this is a forecast. The right decision still depends on your budget, your timeline and the specific unit.
Should I sell my property, or hold and rent it out?
It depends on the asset, and apartments improved most this month.
Resale apartments rose to a median Dh1,514 per square foot. That is 2.2 percent above August and 1.6 percent above last year. Apartment rents edged up to Dh70,000 a year, from Dh68,000, though that is still 4.1 percent below last September.
If you own an apartment and want to sell, you would be selling into a resale market that has strengthened three months in a row. If you hold, the rent is moving up month by month, but over the year the price has moved faster than the rent, so the rent now covers less of what the unit is worth.
Villas point the other way. The median villa rent rose to Dh205,000, from Dh180,000, while resale villa prices eased 2.8 percent. In August I wrote that villa owners were selling into the strongest segment in the data. That is no longer true: resale villas are now 2 percent below last year.
For a villa owner without a deadline, holding through the season looks like the more patient choice on these numbers. Schools are back and the cooler months are starting, which has traditionally lifted demand. That is my reading of past seasons, not a figure in this data.
Plot medians are 35 percent above last year, but with only 237 plot deals in the month they swing hard from one month to the next.
The citywide number is only a starting point. If you want me to look at your actual building, message me on WhatsApp and send me its name.
September against what I wrote in August
Last month's report reached ten specific conclusions. Here is each one next to September's data.
| In August I wrote | September shows |
|---|---|
| Plots caused 73% of the drop in sales value | Plot value recovered to Dh3.8B from Dh2.6B, still below July's Dh6.9B |
| Villas were the only category that held | Villas rose again, to 1,428 deals, and plots and commercial joined them |
| The average deal shrank to Dh2.38M | The average deal grew to Dh2.60M, the highest of the three months |
| Off-plan is where the price softness is | Still true, but off-plan apartments are now 4.8% below 2025, not 8.6% |
| Resale villas were the strongest segment, at +4.5% on 2025 | Reversed: resale villas are now 2.0% below 2025 |
| Apartments softened on both resale price and rent | Resale prices rose a third month and are 1.6% above 2025; rent rose to Dh70K but is 4.1% below last year |
| Financing got harder | Reversed: mortgage value is up 12.7% on August and 37.6% on last year |
| Dubai is a sub Dh2M market by deal count | Still, but 66% of deals were under Dh2M, against 71% |
| Seven in ten deals are a purchase from a developer | 64%, the lowest share of the three months |
| Dubai South was busiest, at about 2,000 deals | Still first, at about 820, with Al Barsha South Fourth close behind |
Three conclusions reversed: the shrinking ticket, the strength of resale villas and the squeeze on lending. Two got stronger: villas kept growing, and resale apartment prices crossed back above last year. One trend did not change direction at all. The deal count fell again.
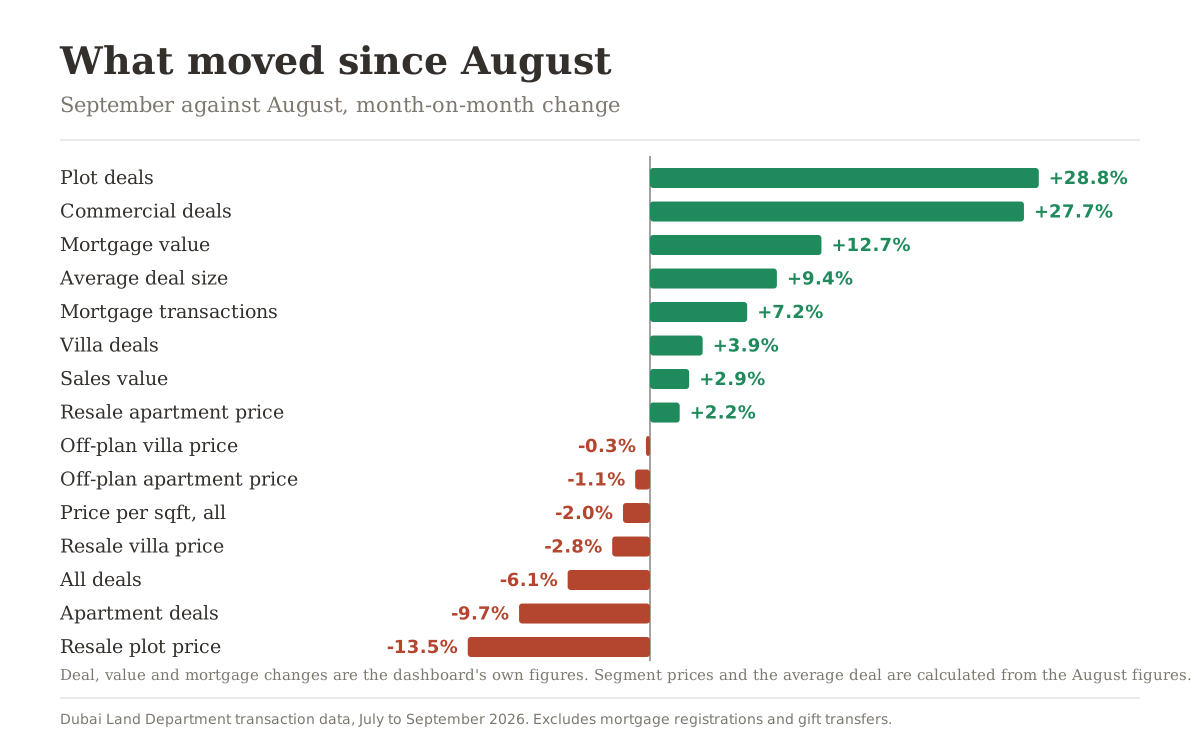
Dubai property market, September 2026, in four numbers
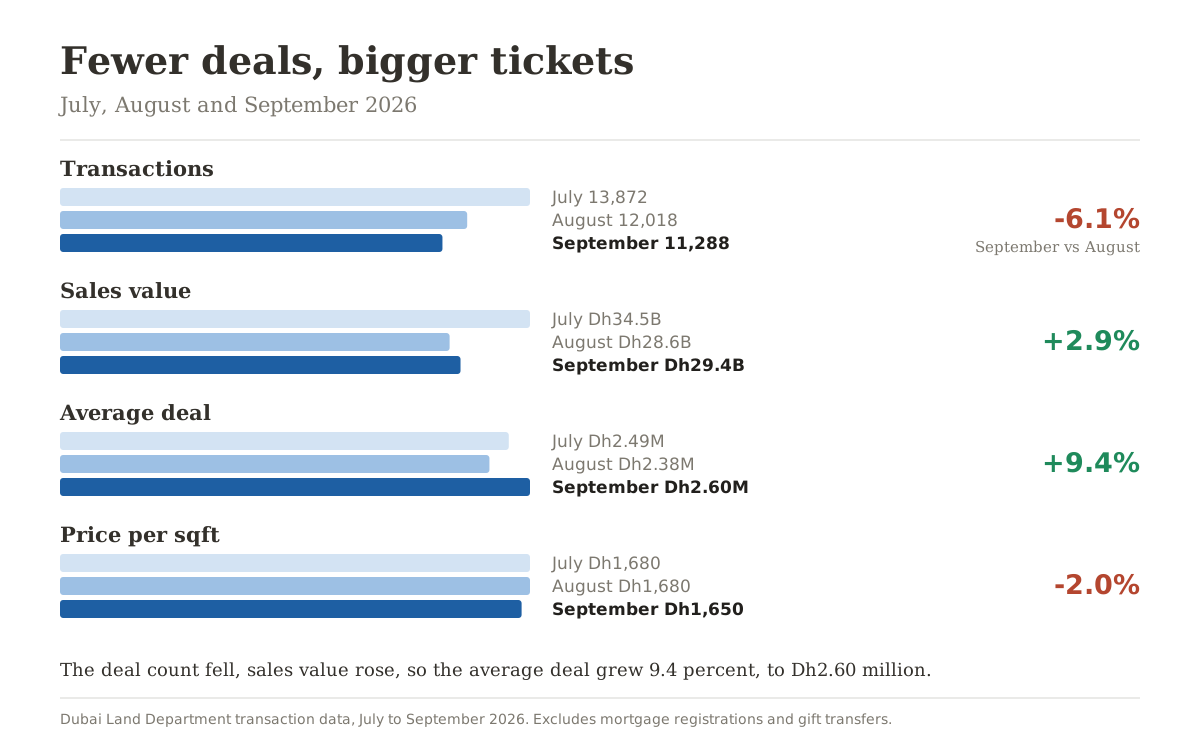
| Metric | July | August | September | vs August | vs Sep 2025 |
|---|---|---|---|---|---|
| Sales volume | 13,872 | 12,018 | 11,288 | -6.1% | -44.4% |
| Sales value | Dh34.5B | Dh28.6B | Dh29.4B | +2.9% | -45.8% |
| Price per sqft | Dh1,680 | Dh1,680 | Dh1,650 | -2.0% | -2.4% |
| Average deal | Dh2.49M | Dh2.38M | Dh2.60M | +9.4% | not calculated |
Read the lines together this time, because two of them moved in opposite directions.
Volume fell for a second month: 13,872, then 12,018, then 11,288. Value did the opposite in September and rose to Dh29.4 billion. When fewer deals add up to more money, the deals got bigger. The average ticket went from Dh2.49 million in July to Dh2.38 million in August, then to Dh2.60 million in September, up 9.4 percent in a month.
That did not come from a square foot getting more expensive. The price per square foot slipped 2 percent, to Dh1,650. It came from more of the deals being larger, pricier homes, which the price bands further down show directly.
The year-on-year lines are heavy, and I am not going to soften them. Volume is 44.4 percent below September 2025 and value is 45.8 percent below. Last September, at about 20,300 deals, was the busiest September in the record back to 2014, so it is a hard month to compare against.
Where the extra Dh0.8 billion came from
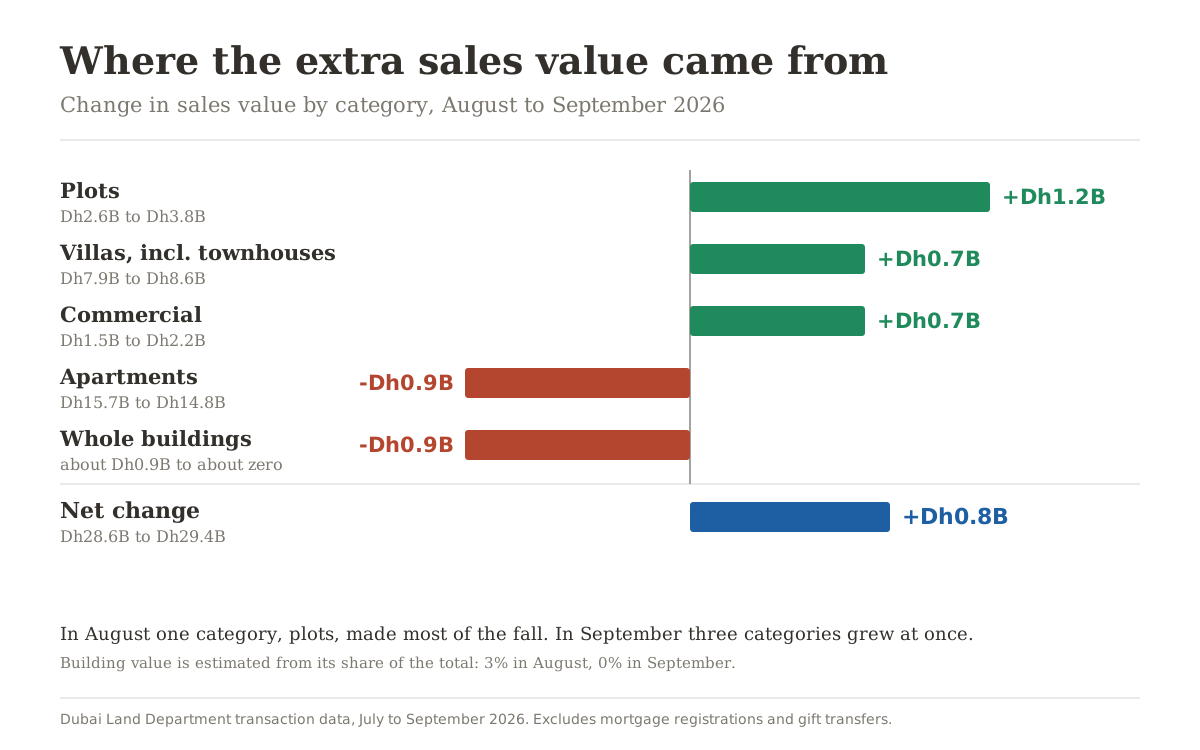
In August one category did most of the damage: plots were 73 percent of the fall in sales value. September is the mirror image. The rise came from three categories at once.
Plot value rose Dh1.2 billion. Villas added Dh0.7 billion, and commercial another Dh0.7 billion. Apartments went the other way, down Dh0.9 billion. Whole-building sales, about 3 percent of August's value or roughly Dh0.9 billion, were close to zero in September. Net, that is the Dh0.8 billion increase.
Take whole buildings out of both months and the four main categories went from Dh27.7 billion to Dh29.4 billion. That is a rise of about 6 percent, not 2.9.
Villas, plots and commercial grew; apartments fell
| Category | July | August | September | Value, September | vs Sep 2025 |
|---|---|---|---|---|---|
| Apartments | 11,759 | 9,974 | 9,055 | Dh14.8B | -47.6% |
| Villas, incl. townhouses | 1,322 | 1,354 | 1,428 | Dh8.6B | -32.7% |
| Commercial | 515 | 420 | 539 | Dh2.2B | +5.3% |
| Plots | 268 | 183 | 237 | Dh3.8B | -37.1% |
Villas rose for a second month in a row: 1,322, then 1,354, then 1,428. The dashboard puts September's rise at 3.9 percent. Villa sales value reached Dh8.6 billion.
Commercial is now the only category above last year. In August I noted that it had barely joined the year-long slowdown, down just 5.6 percent on the year. In September commercial deals rose 27.7 percent on August, to 539, which puts them 5.3 percent above September 2025.
Plots rebounded after a weak August, up 28.8 percent to 237 deals. They are still 37.1 percent below last year, and below July's 268.
Apartments went the other way for a second month: 11,759, then 9,974, then 9,055. That is 9.7 percent below August and 47.6 percent below last year. Apartments are still 80 percent of all deals, so they decide the headline count. In fact the whole fall in volume came from them: apartment deals fell by 919 while the total fell by 730.
| Share of sales value | July | August | September |
|---|---|---|---|
| Apartment | 52% | 55% | 50% |
| Villa | 23%, incl. townhouses | 28%, incl. townhouses | 23% |
| Townhouse | not split out | not split out | 7% |
| Plot | 20% | 9% | 13% |
| Commercial | 5% | 5% | 7% |
| Building | about 0% | 3% | 0% |
From September the dashboard splits townhouses out of villas in its value-share chart. Villas and townhouses together took 30 percent of value, against 28 percent for villas in August. The deal counts above still include townhouses with villas.
Dubai property prices in September 2026: off-plan vs resale
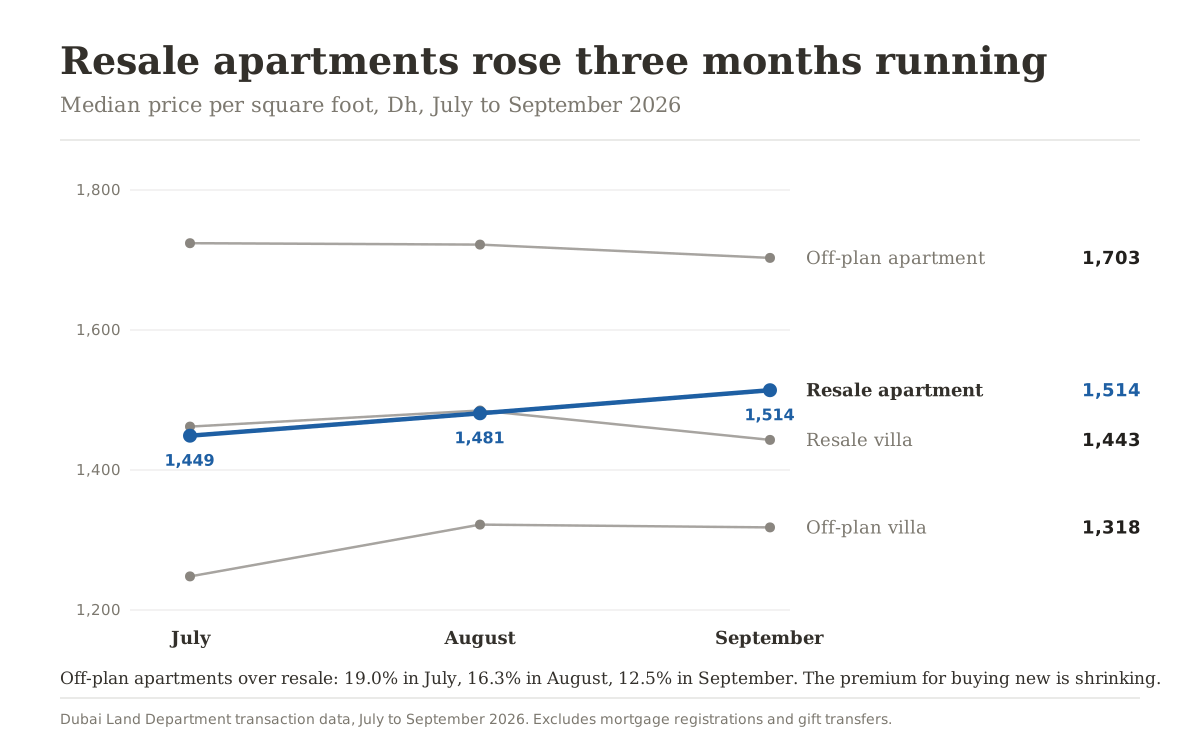
| Segment, Dh per sqft | July | August | September | vs August | vs 2025 |
|---|---|---|---|---|---|
| Off-plan apartment | 1,724 | 1,722 | 1,703 | -1.1% | -4.8% |
| Resale apartment | 1,449 | 1,481 | 1,514 | +2.2% | +1.6% |
| Off-plan villa | 1,248 | 1,322 | 1,318 | -0.3% | +3.5% |
| Resale villa | 1,462 | 1,485 | 1,443 | -2.8% | -2.0% |
| Resale plot | 680 | 920 | 796 | -13.5% | +35.0% |
Resale apartments are the clear riser. The median went from Dh1,449 in July to Dh1,481 in August and Dh1,514 in September. In August they were 2.2 percent below last year. Now they are 1.6 percent above it. In September they also overtook resale villas on price per square foot, for the first time in these three months.
Off-plan villas moved from just below last year to above it: 0.8 percent below in August, 3.5 percent above now, at a price almost identical to August's.
Off-plan apartments are still where the softness is, but there is less of it. They were 8.6 percent below last year in August and are 4.8 percent below now.
The more useful number is the gap between new and resale. The median off-plan apartment cost 19 percent more per square foot than a resale one in July, 16 percent more in August and 12.5 percent more in September. The two medians come from different mixes of buildings and areas, so treat the level loosely. The direction is clear: the premium for buying new is shrinking from both ends, with off-plan easing and resale rising.
Resale villas went the other way. They eased 2.8 percent on August and went from 4.5 percent above last year to 2 percent below it. In August I pointed villa sellers at the resale market as the strongest segment in the data. That has changed, and I would rather say so plainly.
Resale plots are 35 percent above last year, but their median went from Dh680 to Dh920 to Dh796 in three months. With 237 plot deals in the whole city, that is mostly the mix of plots changing hands. I have left off-plan plot prices out entirely. They read Dh540, Dh48 and Dh300 per square foot in the three months, which is a data artefact, not a market.
The second-highest September since 2014
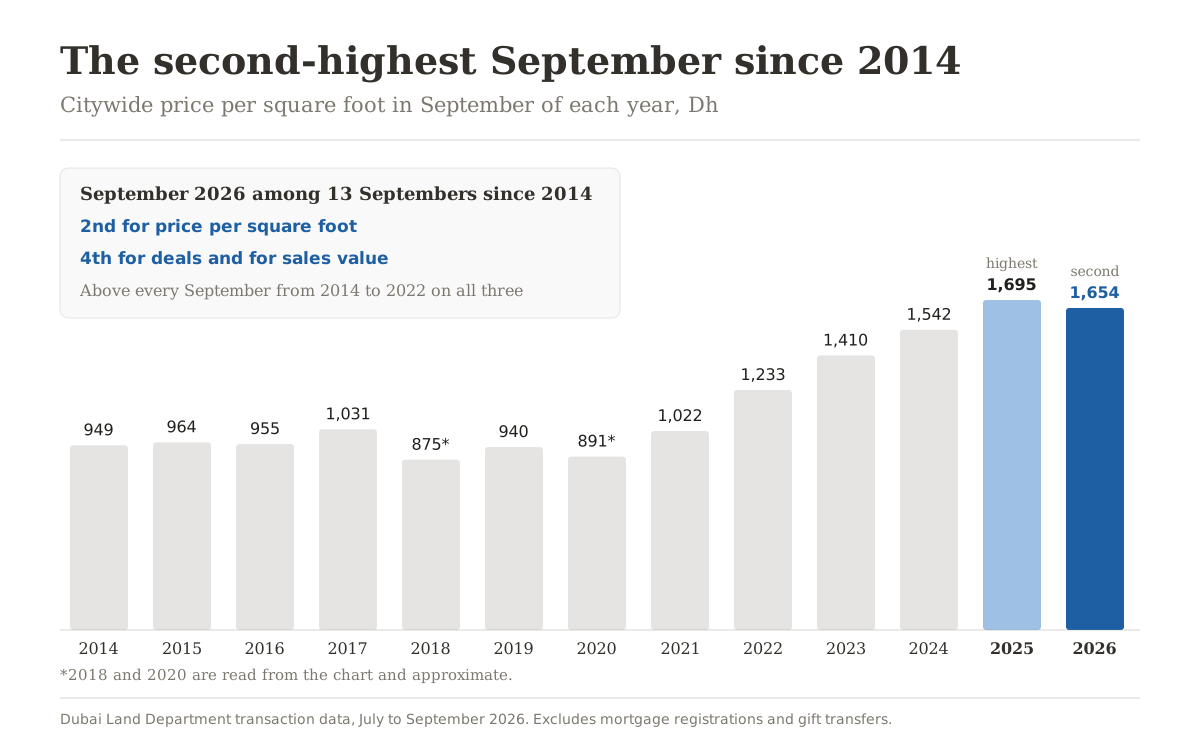
Each bar is that year's September reading. September 2026 came in at Dh1,654 per square foot, second only to Dh1,695 in September 2025 among the thirteen Septembers since 2014. It ranks fourth for deals and fourth for sales value, and it beats every September from 2014 to 2022 on all three measures.
| September | Deals | Sales value | Price per sqft |
|---|---|---|---|
| 2022 | 8.7K | Dh24.3B | Dh1,233 |
| 2023 | 13.6K | Dh37.8B | Dh1,410 |
| 2024 | 18.1K | Dh44.7B | Dh1,542 |
| 2025 | 20.3K | Dh54.3B | Dh1,695 |
| 2026 | 11.3K | Dh29.4B | Dh1,654 |
Last month I quoted the price per square foot as 57.8 percent above August 2014. Run the same sum from September 2014, when the reading was Dh949, and you get about 74 percent. Prices did not jump 16 points in a month. Only the starting month changed: August 2014 read Dh1,066 and September 2014 read Dh949, 11 percent apart in consecutive months. That is why I read the long line by its rank rather than by one percentage.
Thirteen months of deals, and why the next three reports will look weak on the year
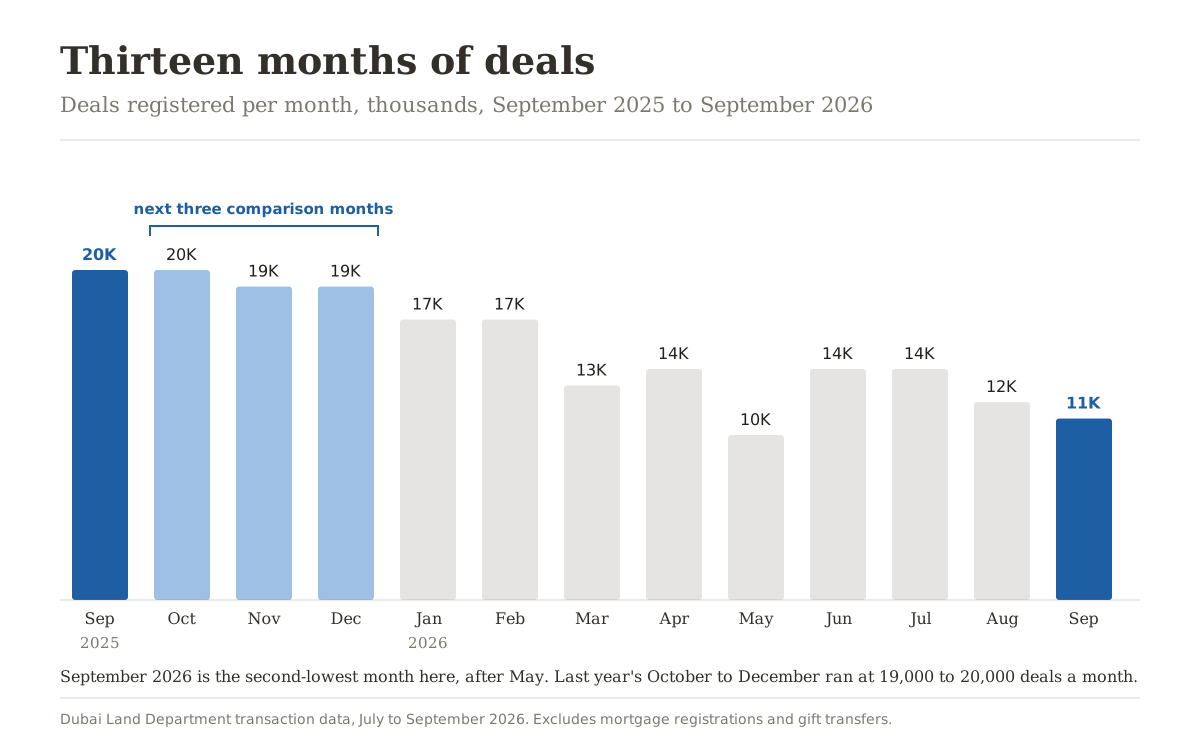
Monthly volume has come down from 20,000 deals in September and October 2025 to 11,000 in September 2026. In these thirteen months only May, at 10,000, was lower.
One practical point for reading the next reports. Last October to December ran at 19,000 to 20,000 deals a month, among the busiest stretches in this window. So the year-on-year numbers will most likely stay deeply negative through December, even if the market improves from one month to the next. That is not a forecast of the market. It is arithmetic about the comparison months.
Dubai rents in September 2026, and the sell-or-hold arithmetic
| Type | July | August | September | vs last year |
|---|---|---|---|---|
| Apartment | Dh65.9K | Dh68K | Dh70K | -4.1% |
| Villa | Dh175K | Dh180K | Dh205K | below last year |
| Commercial | not comparable | Dh118K | Dh115.5K | -16.6% |
Apartment rents rose for a second month: Dh65,900, then Dh68,000, then Dh70,000. They are still 4.1 percent below last September, and that gap is wider than August's 2.9 percent. All three rent types are below last year.
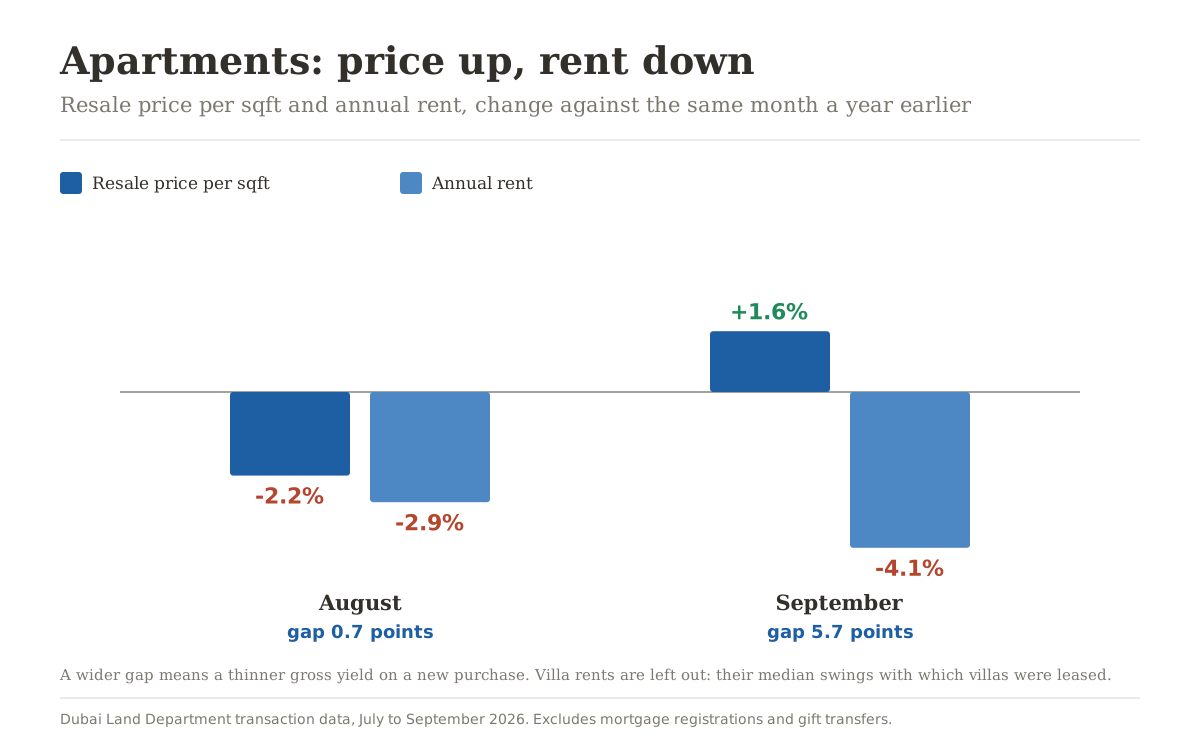
The apartment arithmetic changed this month. In August, resale prices were 2.2 percent below last year and rents 2.9 percent below: a gap of less than a point, so the yield on a typical apartment was roughly where it had been. In September prices are 1.6 percent above last year and rents 4.1 percent below. That is a 5.7 point gap, and it works against the gross yield on a new purchase. For an owner, it means the sale price has improved faster than the rent.
Villa rents rose in dirham terms, to Dh205,000 from Dh180,000, and are still below last year. A villa median depends heavily on which villas were leased in the month, so I am not repeating August's villa yield arithmetic. A jump that size in one month says more about the mix of leases than about the rent level.
Commercial rents are Dh115,500 a year, 2.1 percent below August and 16.6 percent below last year. More commercial units are selling, but the rent on them is still weak.
Run your own unit through the rental yield calculator before you decide. Citywide medians hide large differences between buildings and communities.
Dubai mortgages came back in September
| Metric | July | August | September | vs August | vs Sep 2025 |
|---|---|---|---|---|---|
| Mortgage transactions | 4,298 | 3,593 | 4,038 | +7.2% | +6.5% |
| Mortgage value | Dh16.8B | Dh14B | Dh16.2B | +12.7% | +37.6% |
In August I wrote that financing got harder. September reversed it. Mortgage transactions rose 7.2 percent and mortgage value 12.7 percent on August. Mortgage value is now 37.6 percent above September 2025.
Set that next to the sales lines. Sales value is 45.8 percent below last year, while mortgage value is 37.6 percent above it and the number of mortgages is 6.5 percent above it. Whatever the mix behind it, borrowing has held up far better than the market as a whole.
The resale buyer mix barely moved: 68 percent paid cash and 32 percent used a mortgage, against 67 and 33 in July and August.
If you are buying with finance, get your approval in principle before you reserve a unit. The mortgage calculator shows the loan to value cap for your buyer type and the cash you need on the day, fees included.
Resale gained ground, and deals moved upmarket
| Share | July | August | September |
|---|---|---|---|
| Deals, off-plan / resale | 69% / 31% | 70% / 30% | 64% / 36% |
| Value, off-plan / resale | 59% / 41% | 58% / 42% | 53% / 47% |
In August I wrote that roughly seven in ten Dubai deals are a purchase from a developer. In September the off-plan share fell to 64 percent of deals and 53 percent of value, the lowest of the three months. Turn the shares into counts and resale deals rose from about 3,600 in August to about 4,100 in September, while off-plan deals fell from about 8,400 to about 7,200. The whole fall in volume was off-plan. For owners who want to sell, that is a good sign: more buyers are taking completed homes.
| Price band | July | August | September |
|---|---|---|---|
| Below Dh1M | 43% | 40% | 34% |
| Dh1M to Dh2M | 30% | 31% | 32% |
| Dh2M to Dh3M | 11% | 12% | 15% |
| Dh3M to Dh5M | 8% | 9% | 10% |
| Above Dh5M | 7% | 7% | 8% |
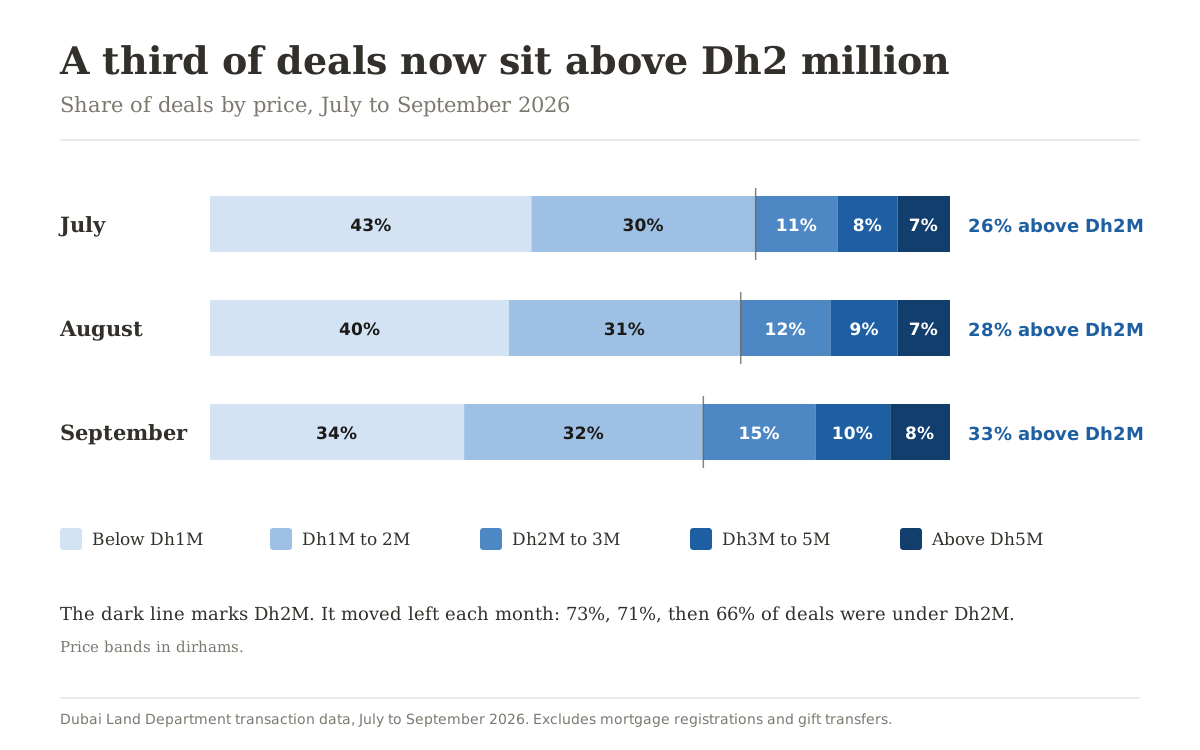
Deals above Dh2 million rose for a second month: 26 percent in July, 28 percent in August, 33 percent in September. In August I called the shift upmarket marginal. In September it was not: the share under Dh1 million fell from 40 to 34 percent in a single month. Dubai is still mostly a sub two million dirham market by count, at 66 percent of deals, but less so than at any point in this report.
This is the other half of the average-ticket story. A square foot did not get dearer. The mix moved toward bigger, pricier homes.
Best-selling projects in Dubai, September 2026
The dashboard ranks the projects that registered the most units in September. Its August overview carried no such table, so where a comparison helps I use July.
| Off-plan apartments | Units | Value | Median price |
|---|---|---|---|
| Valia, Tower | 263 | Dh725.4M | Dh2.3M |
| Binghatti Skyterraces | 252 | Dh238.3M | Dh840.5K |
| Binghatti Skyflame 1 | 226 | Dh162.7M | Dh570K |
| Raw District 2 by Imtiaz, Residential | 186 | Dh184.7M | Dh751.2K |
| Binghatti Skyflame 2 | 133 | Dh104.8M | Dh580K |
| Off-plan villas | Units | Value | Median price |
|---|---|---|---|
| Greenz by Danube | 62 | Dh305M | Dh4.5M |
| Reportage Hills | 53 | Dh102.8M | Dh1.7M |
| The Greens at Sobha Sanctuary | 51 | Dh258.6M | Dh4.2M |
| The Grove at Sobha Sanctuary | 33 | Dh332.1M | Dh9.5M |
| The Brooks at Sobha Sanctuary | 29 | Dh166.4M | Dh5.8M |
Binghatti holds three of the top five off-plan apartment spots: Skyterraces, Skyflame 1 and Skyflame 2, together 611 units worth Dh505.8 million. Valia, the tower I wrote up in August, registered 263 units worth Dh725.4 million on its own, more than the three Binghatti projects combined, because its median ticket is Dh2.3 million against Dh570,000 to Dh840,500 for Binghatti. RAW District 2 by Imtiaz, which I covered in June, was fourth.
Sobha Sanctuary holds three of the top five off-plan villa spots: The Greens, The Grove and The Brooks, together 113 units worth Dh757.1 million. Greenz by Danube sold the most villas, at 62. The Grove at Sobha Sanctuary had the highest median on the list, Dh9.5 million, and Reportage Hills the lowest, Dh1.7 million.
Across both lists the best sellers run from Dh570,000 apartments to Dh9.5 million villas. Demand is not concentrated in one corner of the market.
| Resale apartments | Units | Value | Median price |
|---|---|---|---|
| Dune Residency Dubai | 32 | Dh24M | Dh651.2K |
| Binghatti Apex | 31 | Dh24M | Dh680K |
| Regalia | 20 | Dh28.7M | Dh1.3M |
| Sobha Hartland, Crest Grande | 19 | Dh51.3M | Dh2.5M |
| Peninsula Four, Tower A | 15 | Dh28.8M | Dh1.4M |
| Resale villas | Units | Value | Median price |
|---|---|---|---|
| Damac Lagoons, Portofino | 16 | Dh49.6M | Dh2.6M |
| Mudon Al Ranim 6 | 16 | Dh62.9M | Dh4M |
| Mudon Al Ranim 5 | 16 | Dh65.3M | Dh4.1M |
| The Valley, Elora | 13 | Dh40.2M | Dh3.3M |
| Damac Lagoons, Costa Brava (2) | 12 | Dh37.4M | Dh2.7M |
Some names repeat from July. Reportage Hills and Imtiaz's Raw District buildings were among July's off-plan best sellers too. On the resale side, Sobha Hartland Crest Grande, Binghatti Apex, Regalia and Damac Lagoons Portofino made the lists in both months. When a name repeats across months, the demand behind it is more than one busy week.
The top end: the strongest villa month of the three
| Top apartment sales | Price |
|---|---|
| Como Residences, Palm Jumeirah | Dh71M |
| Muraba Veil, Al Wasl | Dh37M |
| Mr C Residences Jumeirah B3 | Dh37M |
| Bluewaters Residences 3 | Dh36M |
| Serenia Living T3 | Dh30M |
| Top villa sales | Price |
|---|---|
| Eome | Dh260M |
| Dubai Hills, Hills View Community | Dh252M |
| Emirates Hills | Dh128M |
| Signature Villas | Dh110M |
| Lanai Island | Dh91M |
Two villa deals cleared Dh250 million in September: Dh260 million at Eome and Dh252 million at Hills View Community in Dubai Hills. The five biggest villa deals added up to Dh841 million, against Dh363 million in August and Dh290 million in July. Signature Villas and Emirates Hills appear in the villa list in all three months.
Apartments went the other way. The five biggest apartment deals totalled Dh459 million in July, Dh351 million in August and Dh211 million in September. The top one was Dh71 million at Como Residences on Palm Jumeirah, against Dh86 million in August and Dh166 million in July.
In August I wrote that the top of the market had cooled. In September the villa top end had its strongest month of the three, while the apartment top end eased for a second month. At this level one deal moves the whole list, so read it as more activity at the top of the villa market, not as prime values changing.
Where the deals happened
The five most active areas by deal count in September, in rank order. The counts are read from the dashboard's chart, so they are approximate.
- Dubai South, about 820 deals
- Al Barsha South Fourth, about 805
- Wadi Al Safa 3, about 650
- Jabal Ali First, about 540
- Wadi Al Safa 5, about 460
Dubai South has led all three months, but its count fell from about 2,000 in August to about 820, and it now sits barely ahead of Al Barsha South Fourth. Demand at the top of the table is far more evenly spread. Wadi Al Safa 3 is new to the top five, and Wadi Al Safa 4, second in August, dropped out. I looked at Dubai South on its own last week: is Dubai South a good investment?
Sky View's Expo is now monthly: the next one is on 31 October
Hosting an Expo every month is becoming a Sky View tradition. Our Grand Property Expo, Volume 2, ran on Saturday 19 September at the Shangri-La Dubai on Sheikh Zayed Road, and it sold Dh85 million of property in a single day.
There is one cross-check worth making. Nine of September's ten best-selling off-plan projects carry the names of developers who were on the Expo roster: three Binghatti projects, three at Sobha Sanctuary, and one each from Danube, Imtiaz and Reportage. I am not claiming the Expo caused those numbers. It does show that the developers you meet side by side at the Expo are the ones the market is buying from.
The next Expo is on Saturday 31 October 2026. Only the date is confirmed so far, so message me on WhatsApp for details and registration. If you tell me your budget and what you are looking for beforehand, I will have a shortlist of the developers that fit, so your day goes on comparing those rather than every stand in the room.
What I would do this month
Six things, based on the data above rather than on what would be convenient for me.
- If you are buying off-plan, negotiate the terms, not only the headline price: the payment plan, the DLD fee treatment and the unit. Off-plan apartments are still 4.8 percent below last year, but the premium over resale has shrunk to 12.5 percent, so price a completed resale unit in the same area next to it.
- If you are selling an apartment, resale prices have risen three months running and are above last year. That is the market you would be selling into.
- If you own a villa and have no deadline, I see no reason to rush a sale in a month when resale villa prices eased 2.8 percent. Check your own community's numbers first.
- If you are buying an apartment to rent out, do the yield arithmetic carefully. Prices are 1.6 percent above last year and rents 4.1 percent below.
- If you need finance, get approval in principle before you reserve. Lenders were more active in September, with mortgage value up 12.7 percent on August.
- If you are undecided, come to the Expo on 31 October and compare developers side by side before deciding anything.
Where I land
September moved the right way where it counts. Sales value rose on bigger deals. Villa, plot and commercial activity grew. Mortgages came back, with mortgage value 37.6 percent above last year. The price per square foot slipped 2 percent but is still the second-highest September reading since 2014, and the top end of the villa market had its busiest month of the three.
The deal count fell again, and apartments, the bulk of the market, weakened for a second month. Rents are below last year in all three types. The year-on-year comparisons will stay tough until the end of the year.
This is a market to be selective in. Not one to chase, and not one to avoid.
If you want to go through your own situation, whether that is a purchase, a sale or a building you already own, message me on WhatsApp or call me on the same number. I would rather look at your actual numbers than have you act on a citywide average.
Download the two-page September report
This is the two-page summary I send to clients each month, as a PDF. It carries the main numbers from this page, from the market pulse to the best-selling projects.
Dubai market report, September 2026 (PDF)
The two-page report I send to clients each month, as a PDF. Fill in your details and the download button appears here.
A note on the data
Figures are from Dubai Land Department transaction data for July, August and September 2026: DLD direct sales and DIFC sale transactions, excluding mortgage registrations and gift transfers. A few notes on quality, because I would rather show you the seams than a clean number I do not believe.
Month-on-month changes for deals, value and mortgages are the dashboard's own figures. The dashboard calculates them against an updated August count, most likely because late registrations are added to a month after it is first published, so they can differ a little from comparing the two published counts. Villas show +3.9 percent against published counts of 1,354 and 1,428, which would be about 5.5 percent. The villa discrepancy I flagged in August most likely has the same cause. Changes in segment prices against August are my own calculation from the August medians.
Off-plan plot prices read Dh540, Dh48 and Dh300 per square foot across the three months, so I have left them out. Resale plot medians also swing on very few deals.
Villa rent medians move with the mix of villas leased each month, so I describe them by direction only. The dashboard compared July's rents with June, and August's and September's with the same month a year earlier.
From September the dashboard shows townhouses separately from villas in its value-share chart, while the villa deal counts still include townhouses.
Area counts, and the 2018 and 2020 price readings in the long-run chart, are read from charts and approximate. The headline card shows September's price per square foot as Dh1,650 and the long-run chart as Dh1,654, most likely a rounding difference. The value of whole-building sales in August is estimated from their 3 percent share of the total.
Figures sourced from Dubai Land Department transaction data. Provided for information only, not financial or investment advice.
Frequently asked questions
11,288 sales worth Dh29.4 billion. That is 6.1 percent below August's 12,018 and 44.4 percent below September 2025. Sales value moved the other way on the month, up 2.9 percent, although it is still 45.8 percent below last year.
Slightly. The citywide price per square foot was Dh1,650, 2 percent below August and 2.4 percent below last year, and still the second-highest September reading since 2014. The average hides a split: resale apartments rose 2.2 percent on August and are 1.6 percent above last year, while resale villas fell 2.8 percent and are 2 percent below it.
Because the deals got bigger. The average deal rose from Dh2.38 million in August to Dh2.60 million in September, and deals above Dh2 million went from 28 to 33 percent of the total. Plot value rose Dh1.2 billion and villas and commercial Dh0.7 billion each, while apartments fell Dh0.9 billion.
Villas, commercial and plots. Villa deals rose for a second month, to 1,428. Commercial deals rose 27.7 percent to 539 and are the only category above last year, at 5.3 percent higher. Plot deals rose 28.8 percent to 237. Apartments fell 9.7 percent to 9,055.
Resale apartments are rising: Dh1,449, Dh1,481 and Dh1,514 per square foot from July to September, now 1.6 percent above last year. Off-plan apartments are Dh1,703, 1.1 percent below August and 4.8 percent below last year, so the premium for buying new fell from 19 percent in July to 12.5 percent in September. Off-plan villas are 3.5 percent above last year.
The median annual rent is Dh70,000 for an apartment, Dh205,000 for a villa and Dh115,500 for commercial space. All three are below last year: apartments by 4.1 percent, commercial by 16.6 percent, and villas too, despite rising from Dh180,000 in August.
It depends on your numbers. Resale apartment prices have risen three months running and are 1.6 percent above last year, so a seller is selling into an improving market. Rent rose to Dh70,000 but is 4.1 percent below last year, so the price has outrun the rent by 5.7 points and the rent covers less of the unit's value than it did a year ago.
They came back. Mortgage registrations rose to 4,038, 7.2 percent more than August and 6.5 percent more than last year, worth Dh16.2 billion, up 12.7 percent on August and 37.6 percent on last year. In the resale market 68 percent of buyers paid cash and 32 percent used a mortgage.
In off-plan apartments: Valia, Tower with 263 units, Binghatti Skyterraces with 252, Binghatti Skyflame 1 with 226, Raw District 2 by Imtiaz with 186 and Binghatti Skyflame 2 with 133. In off-plan villas: Greenz by Danube with 62 units, Reportage Hills with 53 and The Greens at Sobha Sanctuary with 51.
Two villa deals topped Dh250 million: Dh260 million at Eome and Dh252 million at Hills View Community in Dubai Hills. The top apartment sale was Dh71 million at Como Residences on Palm Jumeirah. The five biggest villa deals totalled Dh841 million, against Dh363 million in August.
Dubai South, at about 820 deals, just ahead of Al Barsha South Fourth at about 805. Wadi Al Safa 3 followed at about 650, Jabal Ali First at about 540 and Wadi Al Safa 5 at about 460. Dubai South has led for three months, but its count fell from about 2,000 in August.
For a selective buyer, September's data is better than August's. Sales value rose to Dh29.4 billion on bigger deals, villas, plots and commercial grew, mortgage value rose 12.7 percent, and the price per square foot is the second-highest September reading since 2014. Against that, deals fell and prices slipped 2 percent, so there is no reason to rush. Developers are offering discounts, DLD fee waivers and flexible payment plans, and the right decision still depends on your budget and the specific unit.
Saturday 31 October 2026. Only the date is confirmed so far, so message me on WhatsApp on +971 58 686 6733 for details and registration. The September Expo sold Dh85 million of property in a single day.